
If you have experienced an incident in your home, you may want to make a claim on your RACV Home Insurance. Go through this step-by-step checklist to make your home insurance claim correctly.
Home Insurance
How to estimate the cost of rebuilding your home
The cost of rebuilding your home isn’t the same as the price you paid for it. Here’s what to include – and what to exclude – when calculating your home’s rebuild cost.
No one expects to suddenly have to rebuild their entire house, but unfortunately, it can and does happen.
One way households can help ensure they're able to rebuild their home after a total loss is to have building insurance adequate for rebuilding your home.
But contrary to popular opinion, the amount you paid for your home usually isn't the amount needed to rebuild it should an insured event occur.
Guide to estimating your home rebuild costs
Why you should include the cost to rebuild when insuring your home
It's important the amount your home is insured for – your 'sum insured' – is sufficient to cover the full cost of rebuilding your home from scratch. The amount should reflect how much a total rebuild would cost in today's prices and be updated regularly.
Insuring your home for the amount it would take to fully rebuild it (in current prices) can help you rebuild your house to the same size and standard should you lose the entire structure in an insured event (such as a fire).
Risks of underinsuring your home
If you insure your home for less than the total amount it would take to rebuild it, there may be financial impacts if your entire home is destroyed. For example, you may not have the funds needed to rebuild your home as it was.
Find out more about what it means to be 'underinsured'.
Market value vs home rebuild cost: what's the difference?
The market value of your home is the amount you are likely to receive if you sold the property in the current market. This is different from the cost of rebuilding your home after a total loss. When estimating your home building sum insured, it's important to base it on the rebuild cost rather than the property's market value.
Land value is another major difference between your property's market value and its rebuild cost. Market value includes the value of the land your property resides on, while the rebuild cost does not.
Gathering accurate, up-to-date information about your property can help you calculate the amount it would take to fully rebuild.
Step-by-step guide to calculating your home rebuild costs
1. Collect key information about your home
The first step in estimating the rebuild cost of your home is to collate some of the property's basic information. This can include:
- your home address
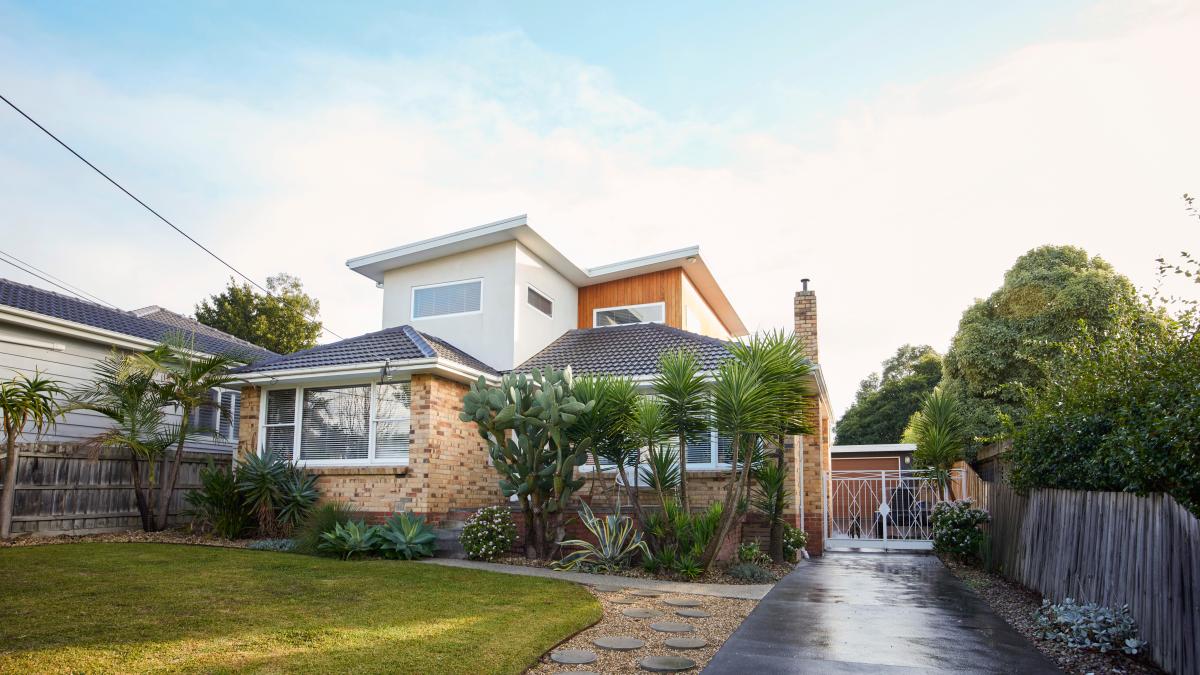
- property type (for example, townhouse, unit, or detached house)
- year it was built
- floorspace (not the land size)
- number of storeys
- construction materials (for example, brick veneer, double brick, or weatherboard)
- roof type and material
- any outbuildings or external features (for example, sheds, garages, pools, decks, and fences)
- any fixed improvements to the home such as solar panels, home solar batteries or EV chargers.
Read more: Are solar panels covered under home insurance?
2. Use a building sum insured calculator
Using a building sum insured calculator* can help take some of the guesswork out of calculating how much it might cost to rebuild your home.
A reputable building sum insured calculator can estimate how much your property's rebuild costs may be in today's prices. It uses current construction industry data to do this, saving you from needing to research this information yourself.
However, it is important to note that these calculators should only be used as a guide. Moreover, they are only as good as the information you put into them – which is why the first step in calculating home rebuild costs is gathering accurate, up-to-date information about your home.
3. Consider professional advice for complex homes
Building sum insured calculators can be helpful but are not a replacement for professional advice. Getting such advice from a qualified surveyor or valuer can be helpful for all property owners, but especially those who own:
- heritage homes
- high-value homes
- custom-built or architecturally designed homes
- homes that have undergone major renovations
- homes built on sloping or otherwise challenging land
- homes that use unusual materials.
4. Add additional costs
The cost of rebuilding your home from the ground up involves more than just the cost of construction. It can also include:
- demolition
- debris removal
- professional fees, such as architect and surveyor fees
- permits
- costs of making the site safe
- compliance costs.
It may be helpful to review your building insurance policy to see which additional costs are included in the sum insured, and which are in addition to the sum insured.
5. Double-check your estimated rebuild cost
The last step is to sense-check the amount you’ve calculated for rebuilding your home. Does it include GST, recent renovations, and any new fixtures? Likewise, does it exclude land value?
The size of your home, as well as how many storeys and external features it has, can impact the rebuild costs.
How often should you review your home rebuild costs?
It’s recommended that you review the cost of rebuilding your property at least once a year. This is because rebuilding costs – such as labour and materials – can change over time, as can your home’s features and fixtures.
It’s also a good idea to review the cost of rebuilding your home after renovations, as these can affect the rebuild value. This may include adding a shed, garage, deck, pool, or fixtures such as solar panels or a home solar battery.
Read more: Should you get an EV or a home solar battery first?
What factors can affect the cost of rebuilding your home?
The following factors can affect how much it may cost to rebuild your home from scratch. They can be helpful to consider when calculating your property’s building sum insured.
Homes with a larger footprint generally require more materials to build and are therefore likely to cost more if you need to rebuild. The size of your home should be calculated using the total floorspace across all storeys of the property, excluding the land size.
More complex home designs, or homes with many rooms, may also affect rebuild costs as they may require more materials to complete.
The cost of common construction materials such as brick, timber, steel and concrete can vary. These materials can also fluctuate in price depending on market conditions, which is why reviewing your building sum insured is important.
Account for the building materials used throughout your entire home, including your roof and any outbuildings.
Hiring skilled tradespeople to rebuild your home can vary in both cost and availability. This can be particularly acute after a major event, when many homes may have been lost and multiple families are looking to rebuild.
The location of your home may impact rebuild costs. Homes in both metropolitan and regional areas – from small, narrow inner-city homes to remote properties – can face challenges in rebuild scenarios.
Certain heritage protections may affect how your home is rebuilt, even after an accidental insured event, such as a fire. This can impact the cost of rebuilding.
Likewise, homes with bespoke features or luxury finishes may cost more to rebuild, and these should be accounted for when calculating your building sum insured amount.
Depending on the age of your home, rebuilding may also require bringing it in line with modern building standards. This can affect your rebuild costs.
Make sure you account for labour costs when calculating your home rebuild costs, as well as the availability of tradespeople.
Common oversights when estimating home rebuild costs
There's a lot to consider when estimating your home rebuild costs. Here are some common oversights people make, and hidden fees they may not account for when calculating the cost of rebuilding their home.
- Failing to account for demolition and site clean-up costs
- Not considering increase in labour and materials
- Overlooking unique home features
- Not accounting for site related costs
- Not updating rebuild estimates after a renovation has been done
- Not using a building calculator or professional assessment as a reliable source
- Using the property’s market value instead of its rebuild cost.
Frequently Asked Questions
No, the cost of rebuilding your home is different to the amount you paid when you bought it.
Generally no, your rebuild costs do not include the value of the land your home is built on.
Yes, you should include the estimated cost of demolition and debris removal when calculating your sum insured.
The information provided is general advice only. Before making any decisions please consider your own circumstances and the Product Disclosure Statement and Target Market Determinations. For copies, visit racv.com.au. As distributor, RACV Insurance Services Pty Ltd AFS Licence No. 230039 receives commission for each policy sold or renewed. Product(s) issued by Insurance Manufacturers of Australia Pty Ltd ABN 93 004 208 084 AFS Licence No. 227678.
* The RACV Home Buildings and Home Contents Calculators provide an indication of rebuilding or replacement costs only and in no way guarantee the amount RACV Insurance may agree to insure your home or contents for. It is your responsibility to check that this amount is enough to cover the rebuilding costs of your home or replacement costs of your home’s contents at today’s prices. Before you decide whether to buy or continue to hold RACV Home Insurance, you should calculate the actual replacement value of your home and contents and consider the information in the Product Disclosure Statement.

